November 15, 2026

The new round of negotiations between Lebanon and the International Monetary Fund reduced the intensity of differences regarding the required reforms, but it did not succeed in extracting a preliminary agreement at the staff level. In this context, a fundamental obstacle has emerged, which is that financial obligations to depositors must be matched with the actual and future financial capabilities of the state and the Bank of Lebanon, in order to avoid new crises that may be more severe than the previous ones.
At the conclusion of the discussions that extended for four days in Beirut, the two parties agreed to intensify work to complete the financial gap law, and it was decided to form a tripartite committee that includes the Ministry of Finance and the Bank of Lebanon, in coordination with the Fund, to draft a consensus and joint draft law that will later be referred to the House of Representatives. Despite this rapprochement, informed sources suggested extending the deadlines for the required legislation beyond the middle of next year, which enhances the possibility of postponing the signing of the financing program, which is worth about $4 billion, and the continuation of work on the Central Bank’s circulars to pay back parts of deposits in installments, pending the approval of the desired law.
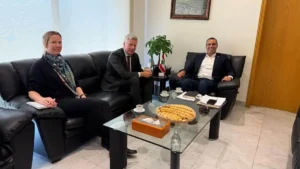
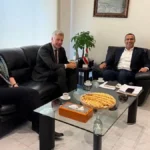
The Minister of Finance, Yassin Jaber, expressed his optimism about reaching an initial agreement during the same week, stressing that the approval of the Financial Gap Law constitutes the obligatory entry point to address the banking crisis. For her part, International Monetary Fund spokeswoman Julie Kozak explained that a team of experts is discussing the strategy for restructuring the banking sector with the aim of developing a comprehensive reform program that restores financial stability, without determining the imminent date for reaching a preliminary agreement.
The complexities of the draft law, officially called “Restoring Financial Regularity and Recovering Deposits,” go beyond the mechanisms for repaying depositors’ funds; Starting from the ceiling of the guaranteed amount of $100,000 in cash, all the way to how deferred payment bonds cover amounts exceeding this ceiling, estimated at about $60 billion. The complications also include determining the state’s contribution to repaying its debts to the Bank of Lebanon, in addition to the legal caveats and political tensions surrounding the possibility of using part of the gold reserves, whether for sale and liquidation or as a guarantee for securities allocated to depositors.
In light of these challenges, the Fund delegation stressed the need to complete the legislative and executive path within a maximum period of the end of the current year, to address the gaps through joint coordination between the executive and monetary authorities before moving to the legislative authority, despite the fact that urgent technical confusions prevented the mission’s final statement from being issued on its early date.