November 14, 2026

Lebanon has been marketing itself for decades as the gateway to the Levant and the natural corridor for trade between the Mediterranean and the Arab depths, a discourse that has been renewed recently in conjunction with talk about a possible role for it in the reconstruction process of Syria. However, the latest international index to evaluate the logistics infrastructure in emerging markets paints a completely different scene, ignoring traditional aspirations, and highlighting a wide gap between Lebanon’s geographical location and what it actually offers to investors and transportation and storage companies.
In this context, Lebanon ranked 44th out of 50 emerging markets included in the “Agility” index for emerging markets in the field of logistics for the year 2026. At the regional level, Lebanon ranked 12th among 13 Arab countries, ahead of Libya alone, while globally it was only ahead of Ethiopia, Myanmar and Libya. Lebanon scored 4.30 points out of ten, compared to a general average of 5 points for emerging markets and 5.11 points for Arab countries, which reflects the superiority of about 86 percent of emerging markets and 92 percent of Arab countries in having a more developed logistical environment.
This low ranking does not reflect a passing event, but rather reflects an upward path of decline. Lebanon ranked 35th in 2024 with a total of 4.66 points, falling to 42nd in 2025 with a score of 4.37 points, reaching 44th in 2026, thus losing a full nine positions in just two years. This decline comes at a time when neighboring countries are recording advanced positions, as the UAE ranked third, Saudi Arabia fourth, and Qatar seventh, while Jordan ranked 18th and Egypt ranked 28th.
The details of the index show that the crisis is deeper than just port efficiency or geographical advantage, as the evaluation is based on four equal weight axes: local logistics market opportunities, international trade opportunities, foundations of the business environment, and digital readiness. Lebanon recorded its weakest performance in the “International Logistics Opportunities” axis – which measures the volume of cross-border trade and the country’s ability to facilitate it – ranking last among all 50 markets, which is the axis that is supposed to constitute its basic competitive base, in addition to coming in lagging positions in the foundations of the business environment axis.
The seriousness of these data lies in their release last February, that is, before the war that broke out in March, and the resulting destruction of the Litani bridges and roads in the south, severe disturbances in shipping traffic, and a decline in exports. This warns that future indicators may carry darker pictures unless the structural causes of this collapse are addressed.
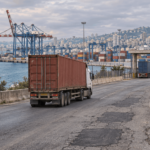
Hence, the bet on Lebanon restoring its regional commercial role, whether in the reconstruction of Syria or in the transit sector, has become dependent on factors that go beyond mere geography. The location alone loses its value in attracting companies if it is accompanied by dilapidated roads, slow bureaucratic procedures, power outages, and lack of financing, especially in light of the heavy investments that neighboring countries are allocating to gain this role. Therefore, Lebanon’s restoration of its position no longer depends on recalling its history as a gateway to the East, but rather requires radical and real reforms that include infrastructure, customs, and the path of digital transformation.